MY BLOG

­

October 2026

Two Moves That Can Get You Into Your First Home Sooner

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.How Long Buying Really TakesFirst, one quick definition. “Breaking even” is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:

“Buyers should think about not just when they can afford to buy, but how long they’d need to stay before owning makes more financial sense than renting.“

So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that’s just under 15 years. But that math relies on two assumptions: that you’re buying a mid-priced home, and that you’re putting 20% down. Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live. A Starter Home Can Get You There Twice as FastA starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area. Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):That works out to about 4.6 years to save and 2.6 years to break even. It won’t erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.You Usually Don’t Need To Put 20% DownYou, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t. Most first-time buyers don’t put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.There’s help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:

“Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase.”

Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.Bottom LineYour first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner. Want to see which starter homes in your area could fit your budget? A local real estate agent can show you.
What Higher Mortgage Rates Mean for Home Sellers

Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too.That’s because today’s buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they’re looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.If you’re planning to sell, that doesn’t mean you can’t compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.Builders Are Competing on the Monthly PaymentNew construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That’s a big difference to a buyer who are feeling the pinch right now.So, How Can Sellers Like You Compete?First, don’t assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer’s rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can’t. That’s why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.Today’s Market Rewards Sellers Who AdaptBuilders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That’s putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That’s an important message if you’re hoping to sell.You don’t automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren’t equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.Bottom LineHigher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with rate buydowns, closing-cost help, price reductions, and other incentives.If you’re thinking about selling, talk to an agent about what buyers are getting from other homes in your area – including new construction – so you can make sure your house is positioned to compete.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.So, what do the forecasts actually say?Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.What the Newest Numbers Actually SayThe panel’s latest forecast has prices climbing every single year through at least 2030.The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.How This Quarter Compares to the PastHere’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.What It Means for Your Next MoveNow, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.Bottom LineWhether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… That’s not necessarily the number you’d get. It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. What Determines Your Real Rate? Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. Even after you find a home you love, other things can have an impact too. For example:A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. There’s a lot that can ultimately have an impact on your actual rate. Your First Step? Getting Pre-Approved.If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. Your lender may recommend a pre-qualification and pre-approval:Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:How To Get Ready for the ConversationAsk your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? Will I get any tax advantages by buying a home – and what are they? What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?How will rate changes in either direction affect me?Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  Bottom LineHeadlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. With the right help, you can find out what your real rate is – and where it can take you.

Why So Many Sellers Are Cutting Their Price Right Now

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.This is what’s actually driving all those price cuts, and why it matters no matter which side of the deal you’re on.42% of Homes for Sale Are Now Carrying a Price CutAccording to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below): Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.What does that mean for you?If you’re selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market’s been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.If you’re buying, it’s easy to assume a price cut means something’s wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that’s exactly the kind of opening you need to get a better deal.Why Sellers Are Adjusting Faster than BeforeHousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year’s peak.Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below): Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.Buyers, You’ve Got Room To Negotiate AgainAt the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below): That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.Bottom LinePrice cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Connect with a local real estate agent to look at what’s actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

November 2025

Would You Let $80 a Month Hold You Back from Buying a Home?

Would You Let $80 a Month Hold You Back from Buying a Home? Simplifying The Market

A lot of buyers are stuck in “wait and see” mode right now. They’re watching rates hover a little above 6% and thinking, I’ll buy once they hit the 5s. Because who doesn’t want a better rate?

But here’s the thing: that 5.99% number might not save you as much as you think.

Affordability is still a challenge. There’s no question about that. But the market has given savvy buyers a head start. Mortgage rates have already come down over the past few months. And the drop we’ve seen saves you more than you’d think.

How Much You’ve Already Saved, Without Realizing It

Let’s put some real numbers to it. Rates peaked for the year in May when they inched above 7%. But since then, they’ve been slowly declining. Now, they’re sitting in the low 6s. And while that may not sound like a big deal, that change translates to real dollars.

According to data coming out of Redfin, the typical monthly payment on a $400,000 home is already down almost $400 since May.

That means if you’re buying a home now, you’re saving hundreds of dollars every month compared to what you would have been able to get earlier this spring. That’s real money that makes a real difference for buyers who paused their plans because they thought homeownership was out of reach.

And while it may be tempting to wait even longer to see bigger savings, that’s a gamble that could cost you. Here’s why.

Where Experts Say Rates Are Headed

For starters, most experts say mortgage rates are likely to stay pretty much where we are today throughout 2026. So, there’s no guarantee we’ll see a rate much lower than what we have now. Only one expert forecaster is saying rates could fall into the upper 5s next year (see graph below): 

a graph with numbers and linesAnd even if rates do dip below 6%, the extra savings you’re holding out for won’t move the needle as much as you might expect.

The Real Math Behind a 5.99% Rate

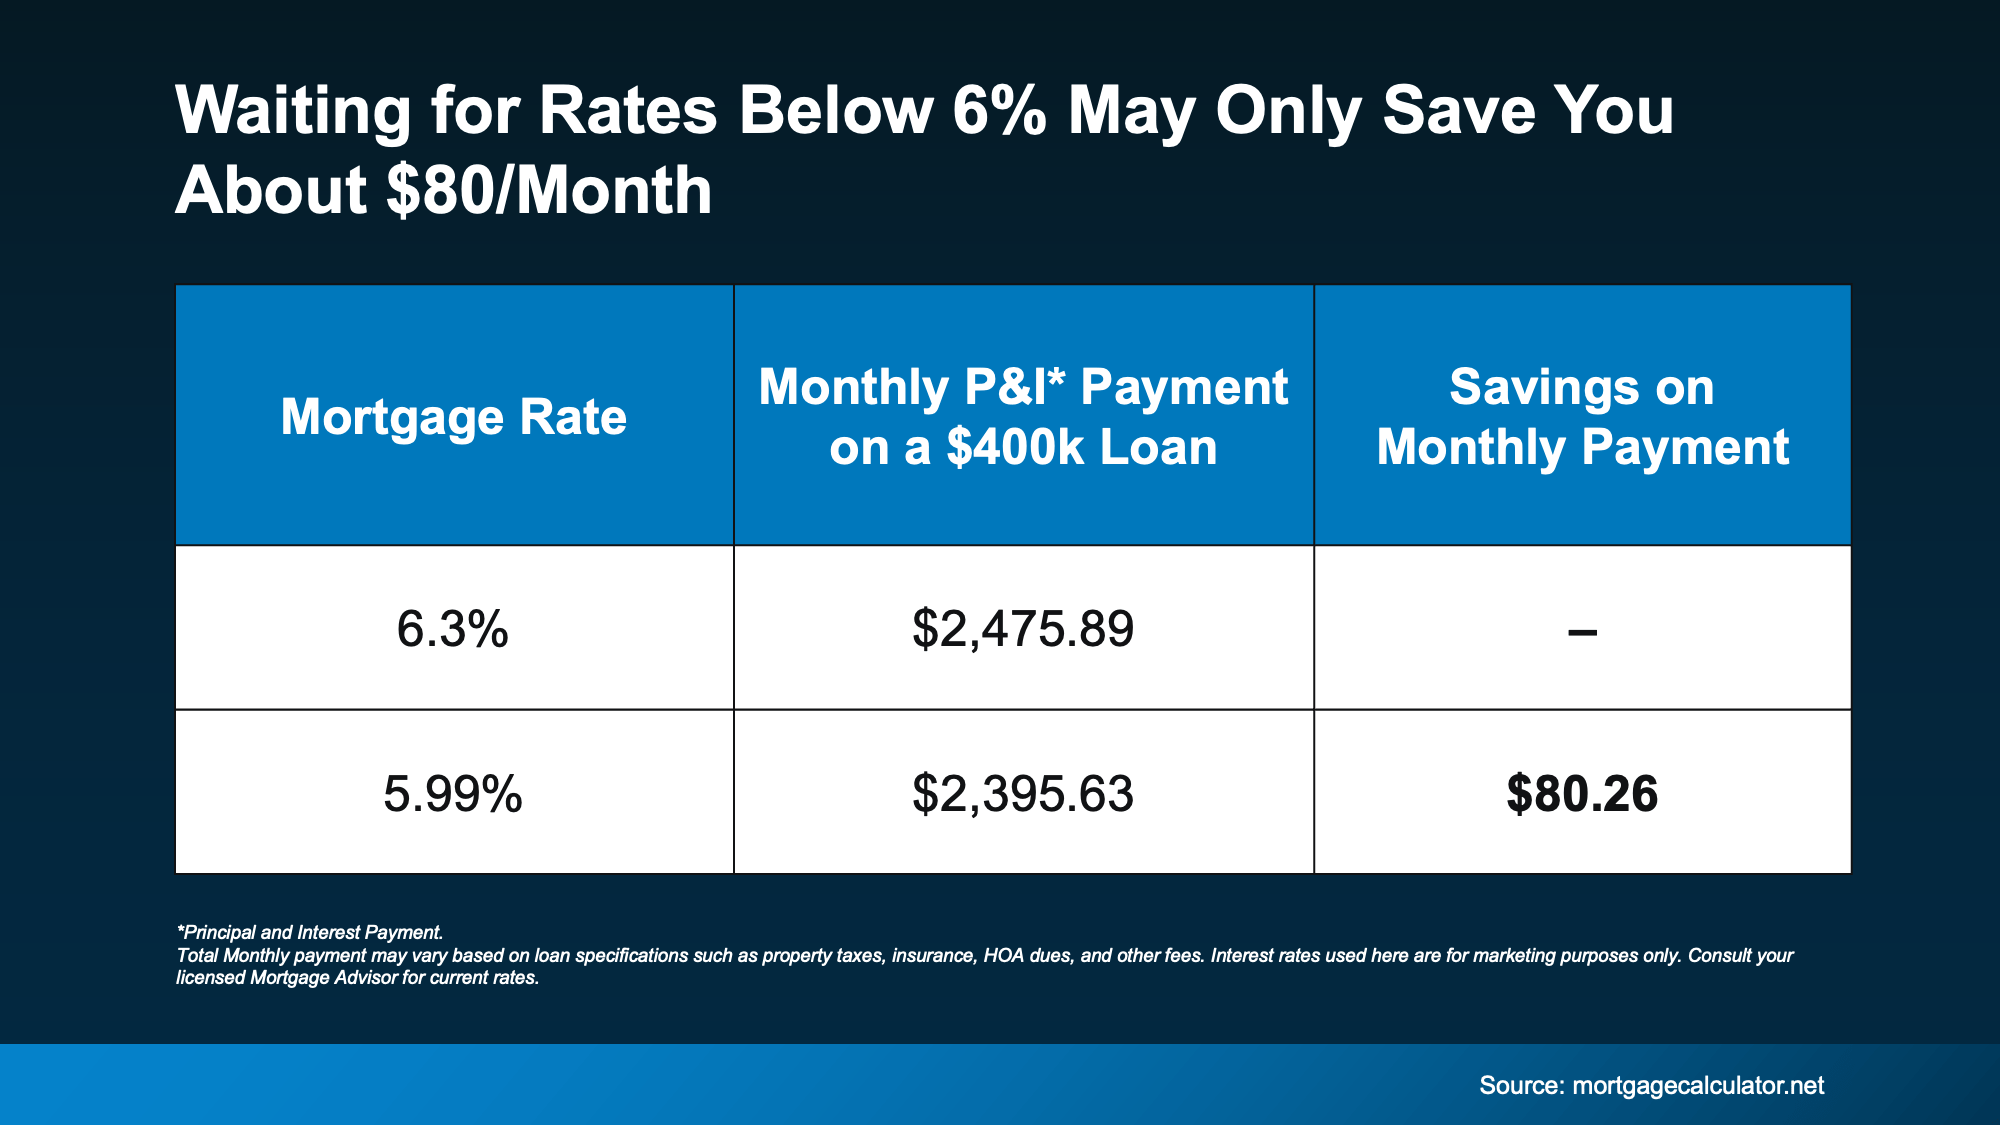
Let’s break it down. If rates come down to 5.99% from where they’ve been lately that’s a difference of only about $80 a month on an average priced home – give or take a bit based on your price point and the rate your lender quotes you (see chart below):

a blue and white rectangular table with white textEighty dollars. That’s it. And for the typical family, that’s about one dinner out (or one dinner in, if you have it delivered). That’s not enough to change the game for most buyers. But the savings of nearly $400 we already have compared to when you paused your search in the spring? That might be. 

So, the question to ask yourself is this:

Is an extra $80 savings really worth the wait?

Because while you’re holding out for that small dip, the bigger opportunity might be slipping away.

When Rates Fall, Competition Follows

Right now, you have more homes to choose from, sellers who are ready to negotiate to get a deal done, and fewer buyers to compete with. But once rates fall below 6%, buyer mindsets will shift and all of that will change.

The National Association of Realtors (NAR) reports that if rates hit 6%, about 5.5 million more households will be able to afford the median-priced home. Even if only a small fraction of them decide to buy, that could mean hundreds of thousands of buyers getting back into the market.

That creates more competition for you, which would push home prices even higher – maybe high enough to cancel out the extra savings you waited for.

So, if you’re waiting for rates below 6%, just keep in mind… that extra $80 may not be worth it in the grand scheme of things.

Bottom Line

You don’t have to wait for 5.99%. You have the chance to move (and save) right now. So, ask yourself: Would you let $80 hold you back from buying a home?

If you find a home you love and the math makes sense, getting ahead may be the best strategy. Connect with an agent or lender to run your numbers. That way you can see what you’re working with in your market.

Are Builders Overbuilding Again? Let’s Look at the Facts.

Are Builders Overbuilding Again? Let’s Look at the Facts. Simplifying The Market

If it feels like you’re seeing new construction signs pop up everywhere, you’re not wrong. Builders have been busy. And it’s left some people wondering: Are we overbuilding like we did right before the 2008 housing crash?

No matter what you may hear in the news, there’s no reason for alarm. In reality, data shows builders aren’t racing ahead, they’re actually starting to tap the brakes.

Builders Are Pulling Back, Not Piling On

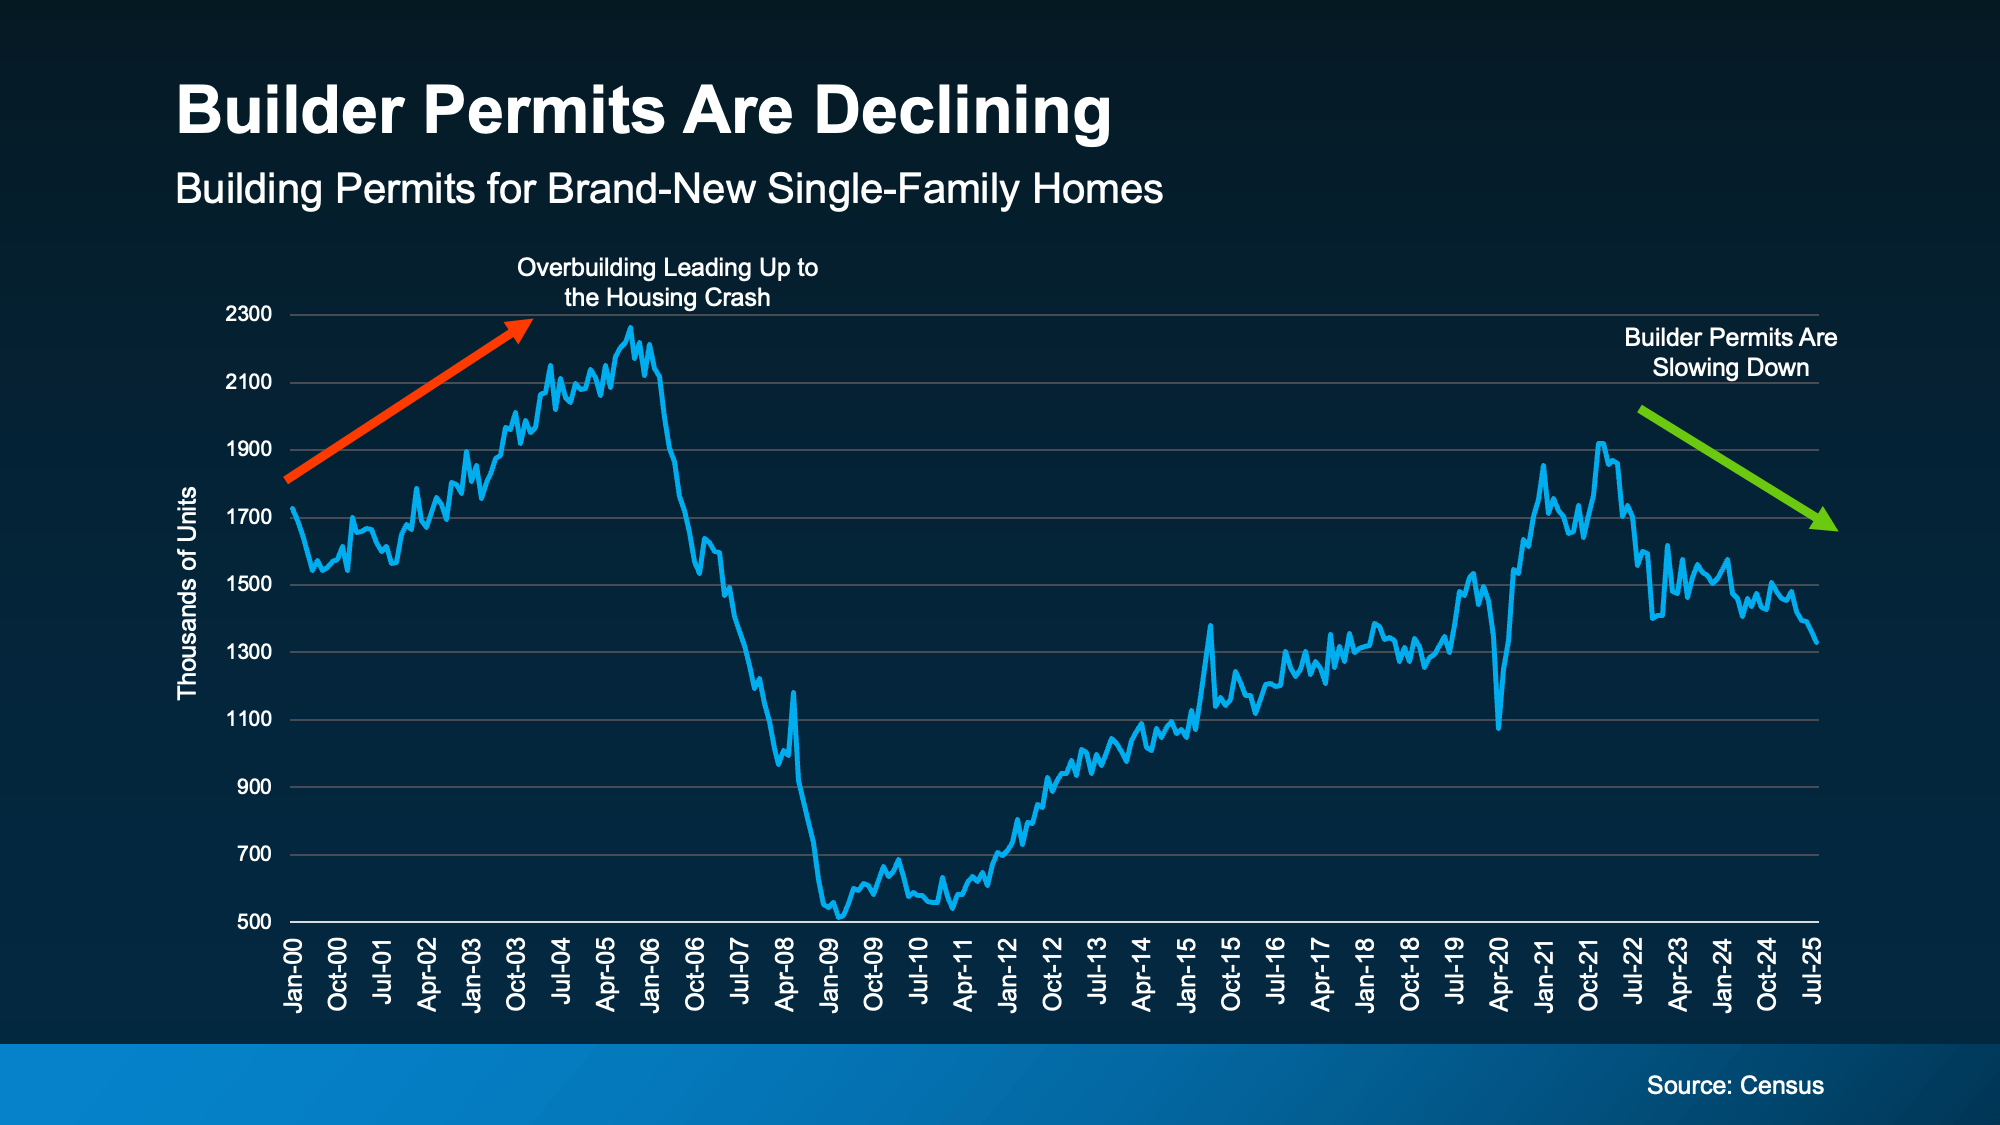
Permits (applications to start building new homes) are one of the best early indicators for what’s next for home construction. And right now, building permits are trending down, not up. Here’s why that’s so important.

In the years before the housing crash of 2008, builders really ramped up their production of single-family homes (the red arrow in the graph below). And unfortunately, they built far more homes than the market actually needed. That oversupply led to falling home prices. That’s what so many people remember, and what they worry will happen again.

But while construction has been picking back up since roughly 2012, we’re not headed for a repeat of the same mistakes. The latest data available shows builders are actually starting construction on fewer homes right now (the green arrow in the graph below):

a graph with blue lines and red textNew data from the National Association of Home Builders (NAHB) confirms that trend. It shows that single-family building permits have fallen for eight straight months.

The Slowdown Isn’t Random, It’s Intentional

Basically, builders are watching and reacting to today’s economic conditions and buyer demand in real time. And they’re pumping the brakes on their pipelines to avoid getting caught with too much unsold inventory. As Ali Wolf, Chief Economist at Zonda, says:

“. . . builders are still working through their backlog of inventory but are more cautious with new starts.”

That’s a big contrast to what happened before the housing crash, when overconfidence led to record-breaking levels of new home construction – even as demand was dropping. Today’s builders aren’t overconfident. They’re listening to the market and adjusting before things get out of balance.

The Regional Picture Tells the Same Story

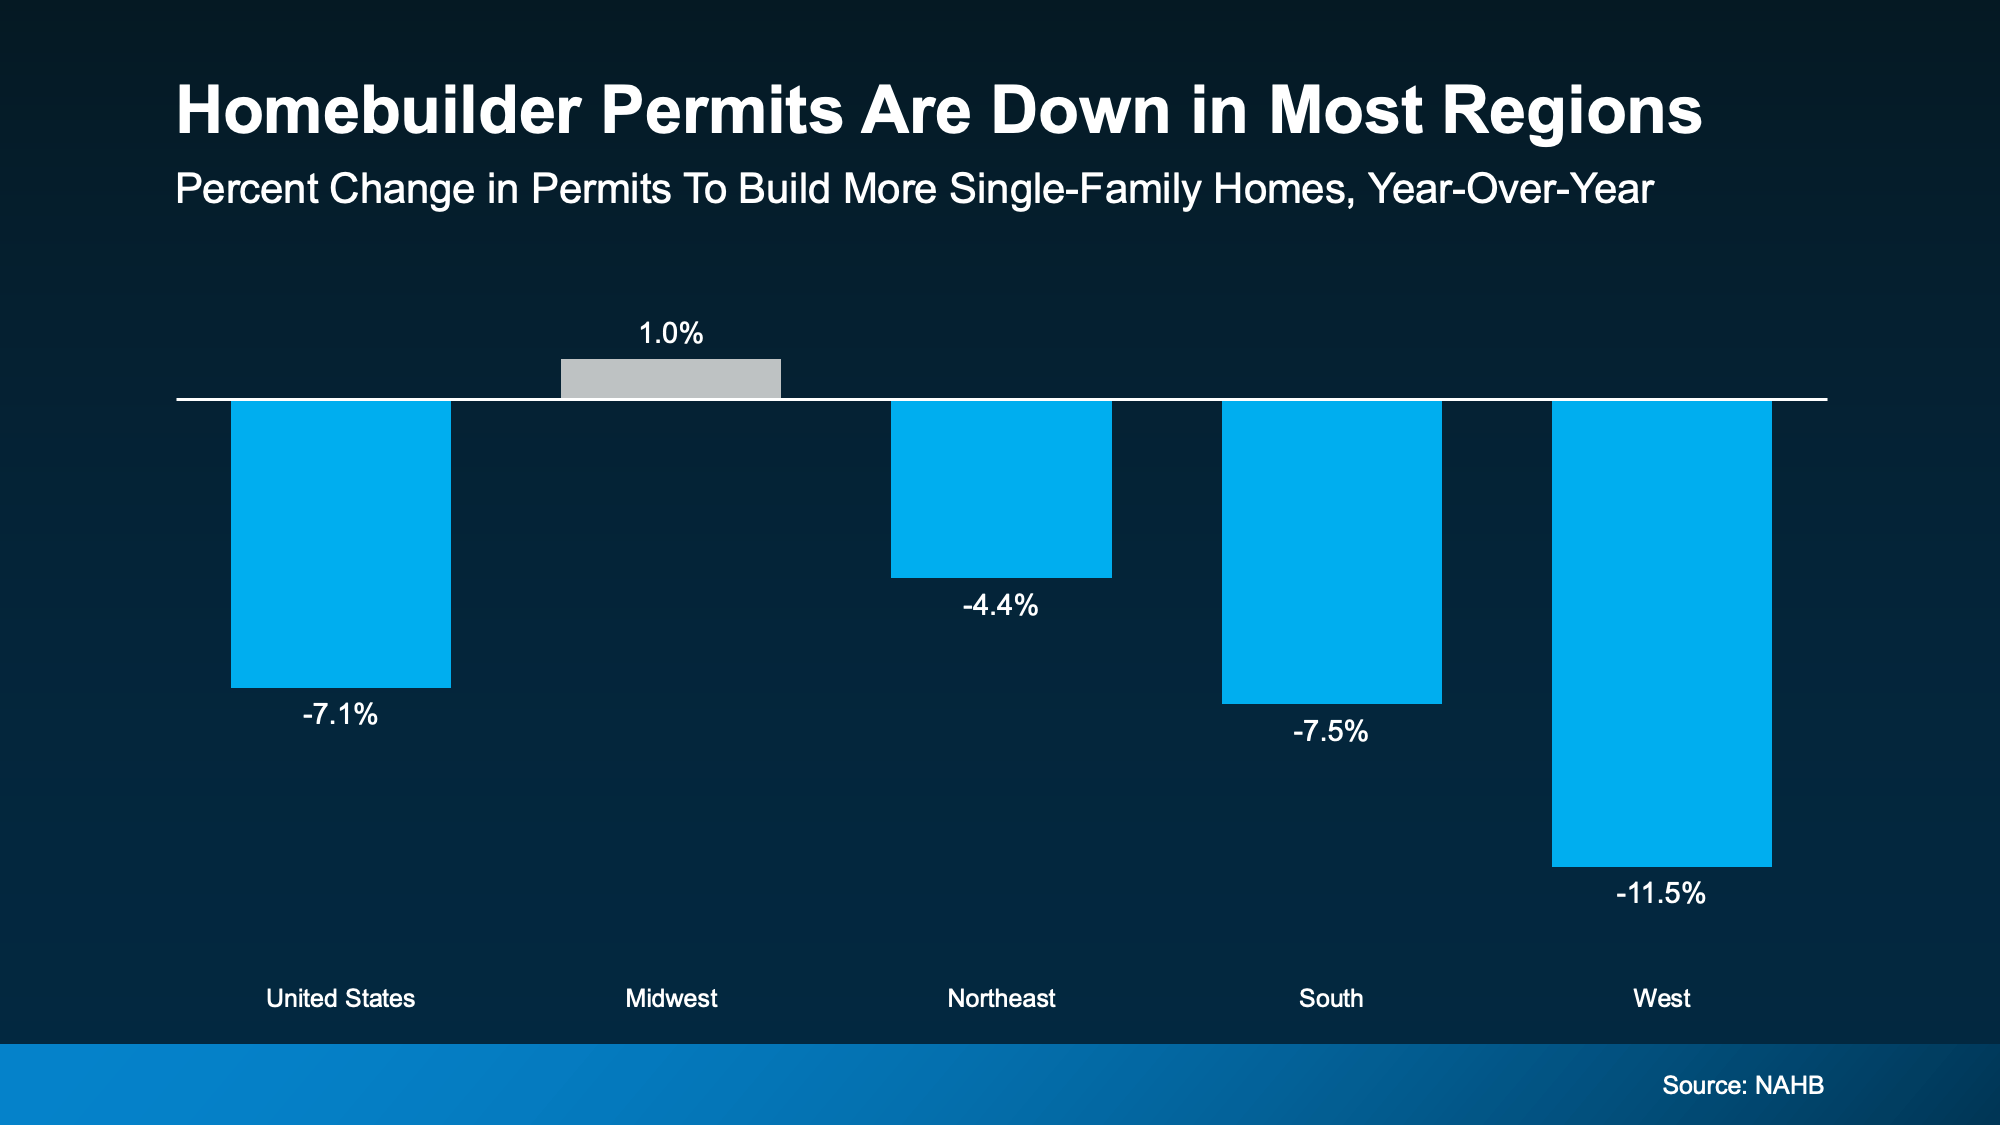
And while inventory is going to vary a lot based on where you live, if you zoom out and look at regional data, the pattern holds almost everywhere (see graph below):

a graph of a number of blue squaresNAHB reports single-family permits are down in nearly every part of the country, with just one region showing a slight uptick. And even there, the growth is so small, it’s practically flat.

Why This Isn’t 2008 All Over Again

In the lead up to the crash, builders kept building long after demand had disappeared. This time, they’re slowing down early, and that’s a good thing.

The market actually needs more homes after years of underbuilding. But builders are making sure they don’t have to overcorrect. They’re being intentional about how many homes they’re building right now.

So yes, you’re seeing more new homes for sale today, but that doesn’t mean we’re oversupplied nationally. It means buyers finally have more options, and builders are pacing themselves to keep things in check. They’re not going to flood the market. And that’s a really good thing for housing overall.

Bottom Line

Seeing more new homes for sale doesn’t mean builders are overdoing it. Since building permits have been declining for eight straight months, it’s clear this isn’t an out-of-control boom. It’s a measured recovery.

If you want to know more about what builders are doing in your area, connect with a local agent.

The VA Home Loan Advantage: What Every Veteran Should Know Right Now

The VA Home Loan Advantage: What Every Veteran Should Know Right Now Simplifying The Market

If you’ve served in the military (or if your spouse has), you have access to one of the most powerful homebuying tools out there. The chance to buy a home without having a down payment.

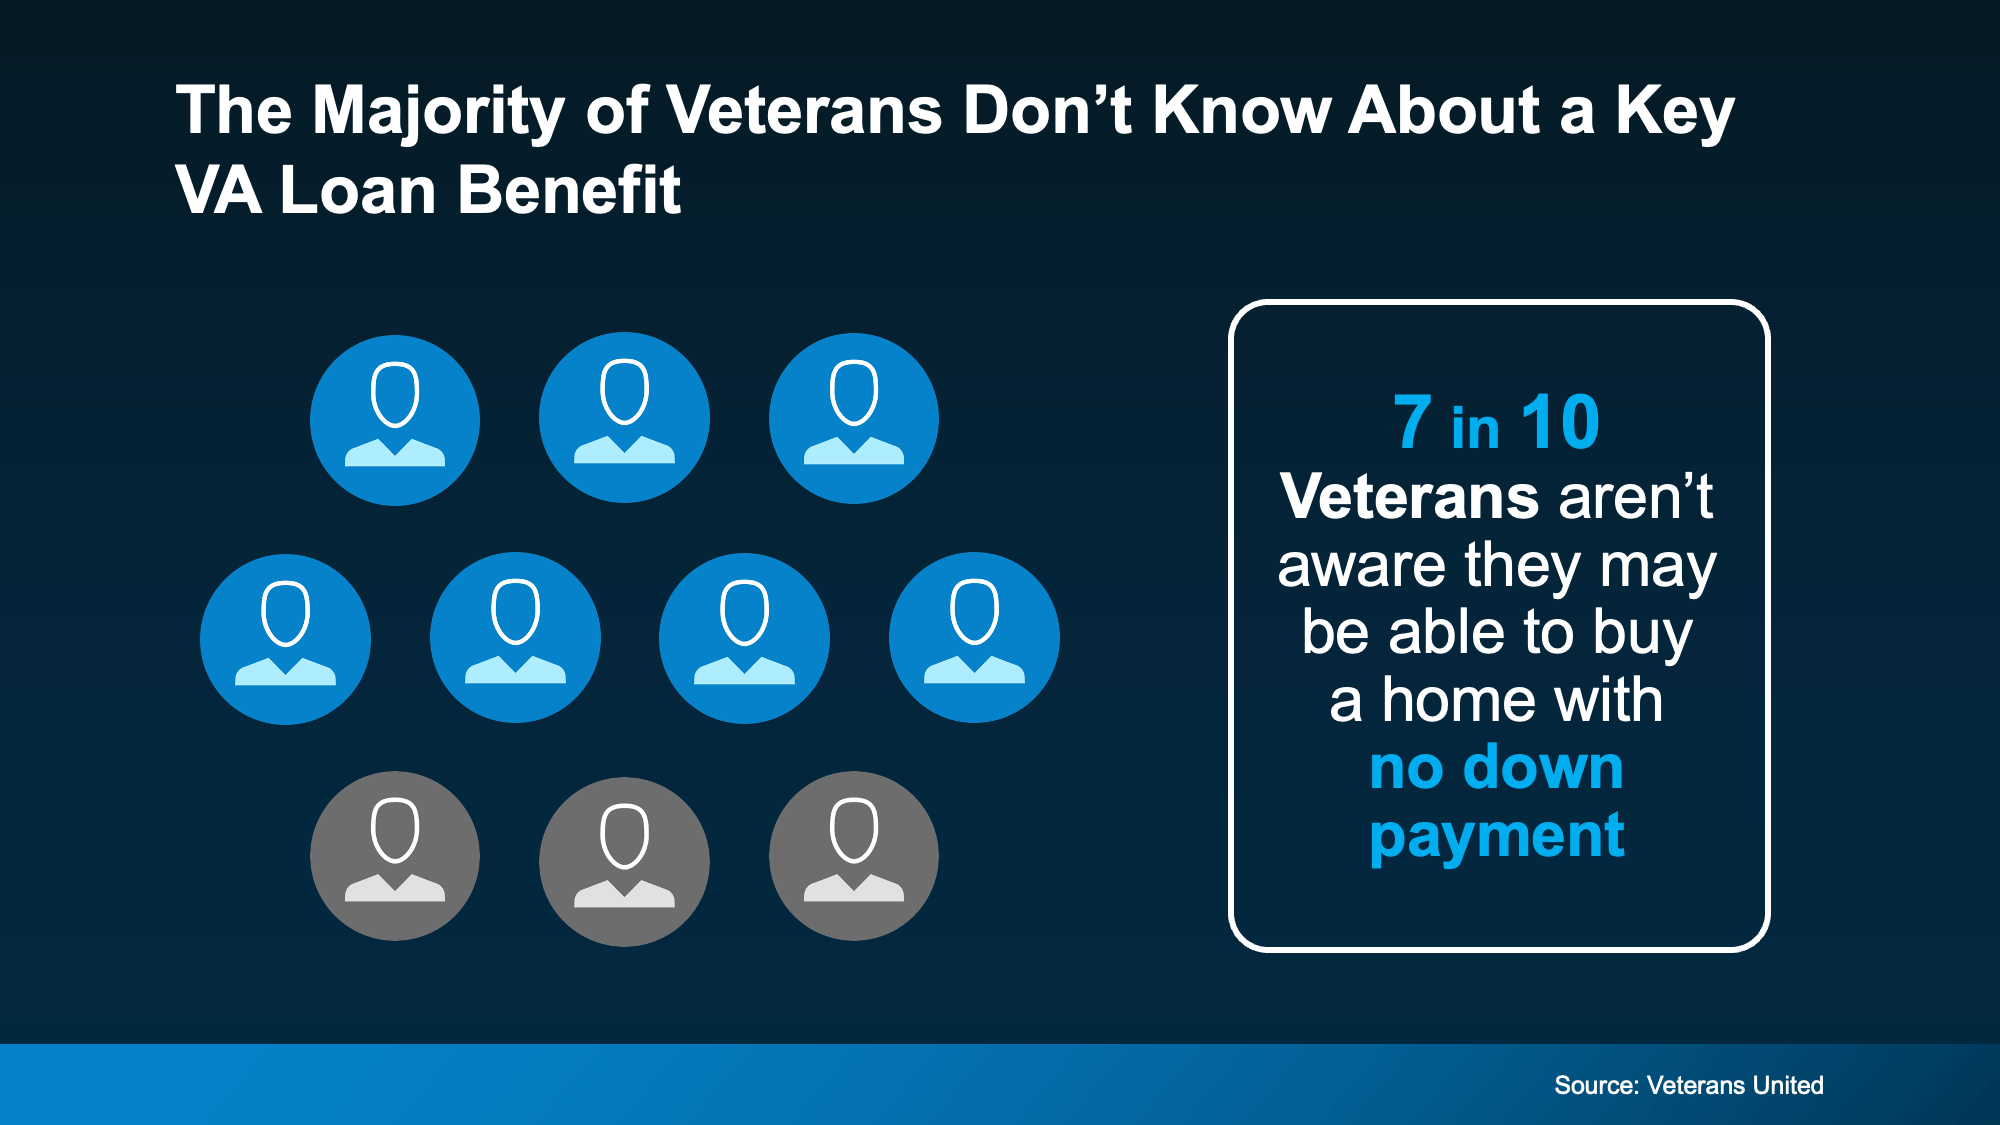
Unfortunately, 70% of Veterans (that’s 7 out of every 10) don’t know about this benefit, according to Veterans United.

a group of people in circlesAnd that’s a big missed opportunity for those who’ve earned this benefit through service. So, let’s break down what you really need to know about Veterans Affairs (VA) home loans right now.

Why VA Home Loans Can Be a Great Option

For nearly 80 years, VA loans have made homeownership possible for millions of Veterans and active-duty service members. Here are just a few of the top perks according to the Department of Veteran Affairs:

  • Options for $0 Down Payment: Many Veterans can buy a home without spending years saving up.
  • Fewer Upfront Costs: The VA limits which types of closing costs Veterans have to pay, helping you keep more cash on hand when you’re finalizing your purchase.
  • No Private Mortgage Insurance (PMI): Unlike many other loan types, VA loans don’t require PMI, lowering your monthly costs.

These features make VA loans a great way for service members (or their family) to build stability, save money, and start creating long-term wealth through homeownership.

Can You Still Get a VA Loan with the Government Shutdown?

But lately, there’s been some confusion about whether VA loans are still available due to the government shutdown. And that uncertainty has kept some Veterans from taking the next step.

While there may be processing delays, Veterans United explains you can still get a loan:

“There’s been a lot of confusion and uncertainty about how a government shutdown will affect VA home loans . . . The good news is that the shutdown has minimal impacts on VA lending. Lenders are still able to order appraisals, obtain a borrower’s Certificate of Eligibility, submit the VA Funding Fee and more. In short, Veterans are still able to use their home loan benefit to buy a home or refinance an existing mortgage.”

So, despite the headlines, you can still use your VA home loan benefits today. The process is ready when you are. It just may take more time to go through.

Why the Right Agent and Lender Matter

Just remember, using your VA home loan is easier (and smoother) when you have the right team behind you. As VA News puts it:

“Choosing a military-friendly broker or agent who understands the VA home loan application process can make all the difference in the homebuying experience. Finding the right agency or brokerage is just as important as locking in a good VA mortgage lender. Communication is key to getting to the loan closing table.”

A knowledgeable agent and an experienced lender can help you navigate every step, all the way from qualifying to closing. With their help, you can make sure you’re getting the most out of your benefits.

Bottom Line

If you’re a Veteran, a VA home loan is one of the most valuable benefits you’ve earned through your service. It offers options for no down payment, limited closing costs, and more.

Want to learn more? Talk to a lender so you can take full advantage of the benefits you’ve earned.

What a Government Shutdown Really Means for the Housing Market

What a Government Shutdown Really Means for the Housing Market Simplifying The Market

There’s been a lot of talk lately about how a government shutdown impacts the housing market. You might be wondering: Is it causing everything to grind to a halt?

The short answer? No.

The housing market doesn’t stop. It keeps moving. Homes are still being bought and sold, contracts are still being signed, and closings are still happening. The difference is that a few parts of the process may slow down a little, but overall, the market continues to function.

Here’s What Typically Happens

Whenever the government shuts down, some federal agencies temporarily close or scale back their operations. That can cause a few hiccups in real estate, especially when it comes to processing certain types of government loans and insurance requirements:

  • “Applicants for FHA, VA, or USDA loans—which account for about one-quarter of all mortgage applications—may encounter significant processing delays due to agency furloughs.” – Selma Hepp, Chief Economist at Cotality
  • “By recent estimates, more than 2,500 mortgage originations per working day are at risk of delays during a shutdown . . .”  – Zillow
  • Flood insurance approvals may also be paused. The National Flood Insurance Program can be temporarily affected, which delays closings in flood zones.

Even with those challenges and delays, most transactions still go through. Buyers keep buying, sellers keep selling, and agents keep helping people move forward.

The Housing Market Usually Bounces Back Fast

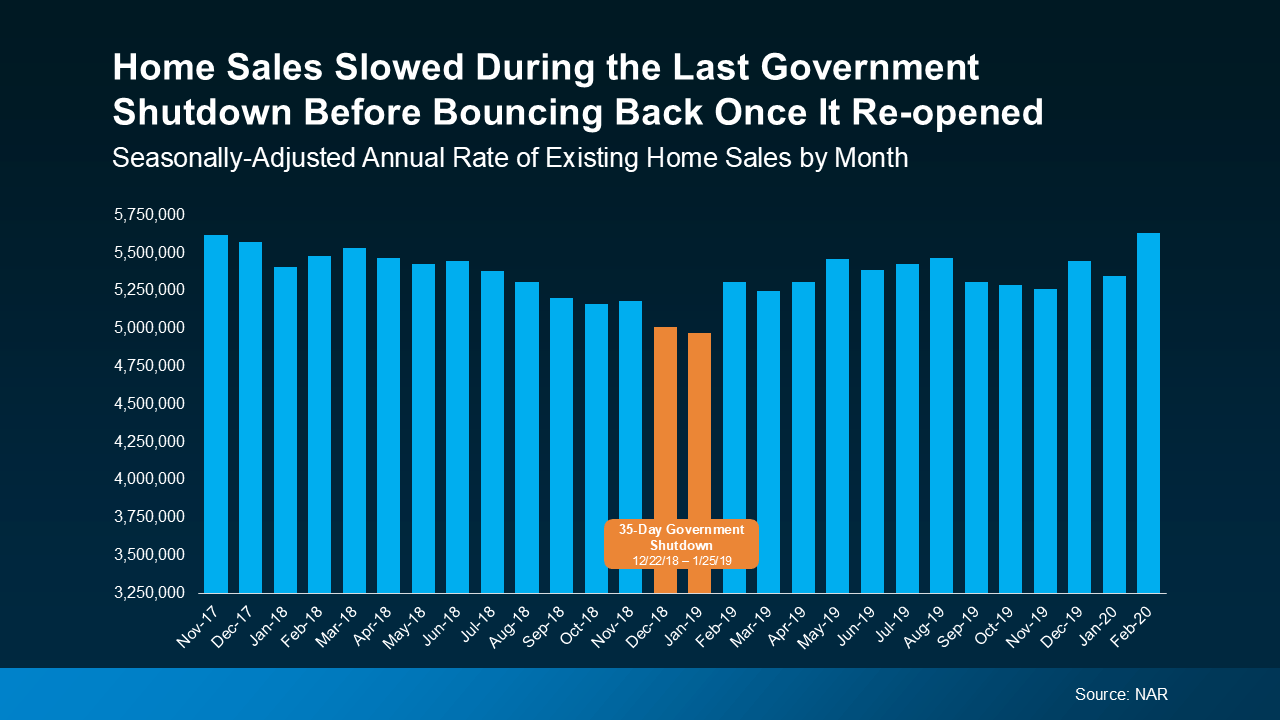
And you can see that play out in this data. If you look back at the most recent government shutdown that began at the end of 2018 and lasted for 35 days, sales activity dipped very slightly during the closure but picked right back up once the government reopened.

Data from the National Association of Realtors (NAR) shows existing home sales slowed for about two months, and then rebounded quickly as delayed closings worked their way through the system when the government reopened (see graph below):

a graph of blue and orange linesWhat’s important to note is that the slowdown you see in the orange bars on this graph wasn’t simply due to seasonality in a typical housing market cycle. The sharper, shorter drop in this case lines up exactly with the 35-day government shutdown, and then sales bounced back as soon as it ended.

What This Means for You

If you’re in the middle of buying or selling a home, don’t panic. Most deals will still move forward, even if it takes a few extra days. Jeff Ostrowski, Housing Market Analyst at Bankrate, explains:

“If you’re expecting to close in a week or a month, there could be some slight delay, but I think for most people, it’s probably going to be a blip more than a real deal killer.”

And if you’re just starting to think about buying or selling, this could actually work in your favor. Some buyers and sellers may become cautious and pause their plans during times of uncertainty, like this, and that can open a short window of opportunity.

When fewer people are active in the market, well-prepared buyers may find less competition for homes, and motivated sellers may be more willing to negotiate. These brief slowdowns often create a moment where you can make a move that would be harder once activity ramps back up.

Bottom Line

A government shutdown can cause short-term delays for some buyers, but it doesn’t derail the housing market. The last time this happened, sales picked back up as soon as the government re-opened.

If you’re unsure how this might affect your plans, or just want to make sense of what’s happening, connect with a local real estate agent.

Why Your Home Equity Still Puts You Way Ahead

Why Your Home Equity Still Puts You Way Ahead Simplifying The Market

If you’ve seen headlines about home prices dropping, it’s easy to wonder what that means for the value of your home too. Here’s what you really need to know.

Even with small price declines in some markets, data shows you’re likely still way ahead. And that’s thanks to your home equity.

The Relationship Between Home Prices and Equity

Home equity moves in sync with home prices. When prices rise, equity builds. When prices cool (even just slightly), equity growth does too. Here’s how that’s played out lately.

After the record-setting home price surge of 2020 and 2021, a little cooling was inevitable.

Back then, the number of homes for sale hit a record low. That caused home values (and your equity) to shoot up significantly as buyers fought over limited inventory.

But prices couldn’t continue to rise at that intense pace forever. The market had to moderate at some point, and that’s exactly what we’re seeing right now. 

As more homes have come on the market this year, price growth slowed – so, equity gains did too. And that doesn’t mean you’ve lost ground.

Putting it into Perspective

You probably still have far more equity than you did just a few years ago. And that puts you in a strong position if you want to sell. Here’s the data to prove it.

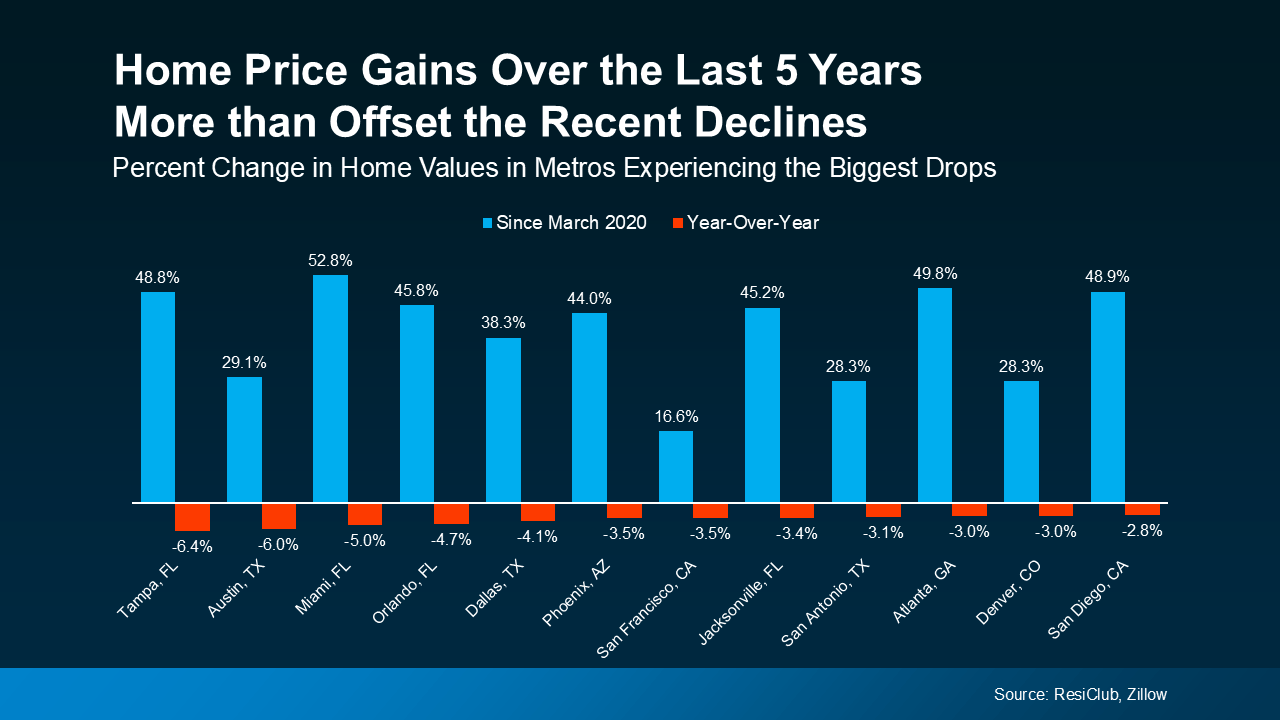
According to research from Zillow, home prices have risen a staggering 45% nationwide since March of 2020. That’s a big jump.

And in the majority of markets, prices are still rising, just at a much slower pace. But even in the metros where prices are experiencing the biggest declines (the ones making the headlines), the average drop is only about -4%.

So, what’s that really mean? In most places, prices are on the rise, so this isn’t even a concern. But in the few metros where prices are cooling off a bit, the 5-year gains more than offset those small dips.

a graph of a number of peopleIn other words, these modest declines can’t erase years of growth. Homeowners who’ve been in their houses for several years are still way ahead. Big time. And that’s true pretty much everywhere.

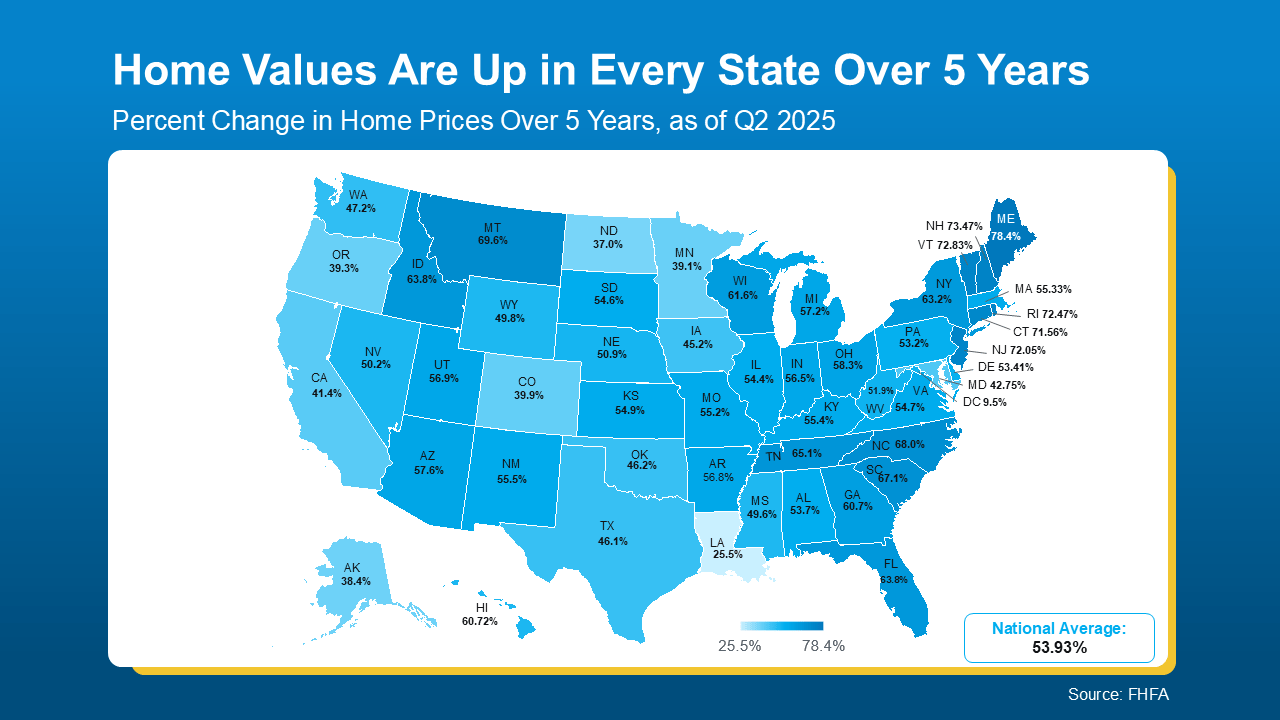
Data from the Federal Housing Finance Agency (FHFA) helps paint this picture. Let’s cast a slightly wider net and look at a state-by-state level this time. Every single state has seen prices go up over the last 5 years. And that means homeowners in each state have much more equity than they did just 5 years ago (see graph below):

a map of the united statesOdds are, in most places, if you’ve owned your home for more than a few years, you’ve already built the kind of equity many people could only dream about before the pandemic. And if you sell, you can use it to help you downsize, or move up.

And just in case you’re worried prices will crash and your equity will take a bigger hit in the near future, here’s what Jake Krimmel, Senior Economist at Realtor.com, has to say:

“The slight recent declines in aggregate value and total home equity are not cause for concern . . . Although the market is coming into better balance, large price declines nationally are extremely unlikely in the near term . . .”

The price moderation we’ve seen lately isn’t a cause for concern. It’s a signal of a market that’s finding its balance again after several years of unsustainable price growth. And after several years of major price appreciation, most homeowners are still in an incredibly strong position.

Bottom Line

Even with prices coming down in some markets, today’s homeowners are still sitting on near record amounts of equity.

If you’re wondering how much equity you have (or how far ahead you really are), connect with a local agent.

You might be surprised by what your home is actually worth today.